Withdrawal planning asks one question: if I take this much out each year, adjusted for inflation, how long does the money last? The honest answer is a distribution, not a number, and this page explains the two ways of estimating it that the Financial Freedom Travel Calculator offers.
The deterministic model
Assume a fixed annual return, a fixed inflation rate, fixed fees and a flat tax on withdrawals, and run the years forward: start balance, minus the grossed-up withdrawal (spending minus income, divided by one minus the tax rate), times one plus the net return. The calculator's moderate scenario does exactly this; the conservative scenario lowers the return by two points and raises inflation by one; the optimistic does the reverse. The output is a trajectory and a year the money runs out (or the whole horizon survived). Its virtue is transparency; its vice is that real returns are not fixed.
Sequence of returns
Two retirements with identical average returns can end very differently if one meets a bear market in year two and the other in year twenty. Withdrawing from a falling portfolio locks in losses. Early retirees are more exposed because the horizon is longer, and travellers more exposed still because their spending is lumpy and their ability to earn their way out is often lower. The deterministic model cannot see this; the probabilistic one can.
The Monte Carlo model
Draw 2,000 random return sequences from a distribution with your mean and volatility (the calculator uses lognormal annual returns), run each one through the same withdrawal rule, and count how many last the horizon. The result is a success percentage and the spread of end balances. It is a better picture of uncertainty than a single line, and still a model: it assumes returns are independent year to year, ignores valuation, and knows nothing about your behaviour when the balance halves.
Reading the output
- Years funded (deterministic): a planning figure under the assumptions, not a prediction.
- Success percentage (Monte Carlo): 85 percent means 15 percent of simulated paths ran out; whether that is acceptable is your decision, and the common fix is flexibility rather than a bigger portfolio.
- Year-1 withdrawal rate: the figure to compare with the literature (3 to 4 percent is the usual planning band for long horizons).
- The destination table: how many months a year your travel budget covers in each place; the cheapest lever on the whole problem.
Flexibility is the real safety margin
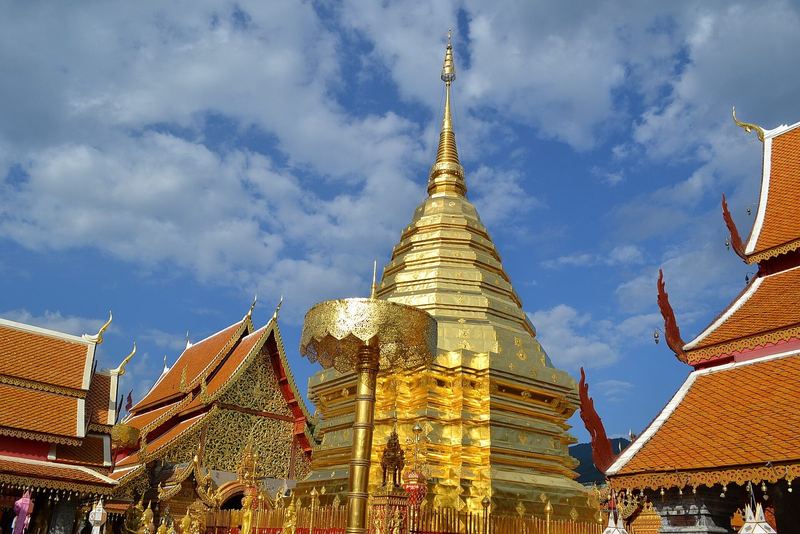
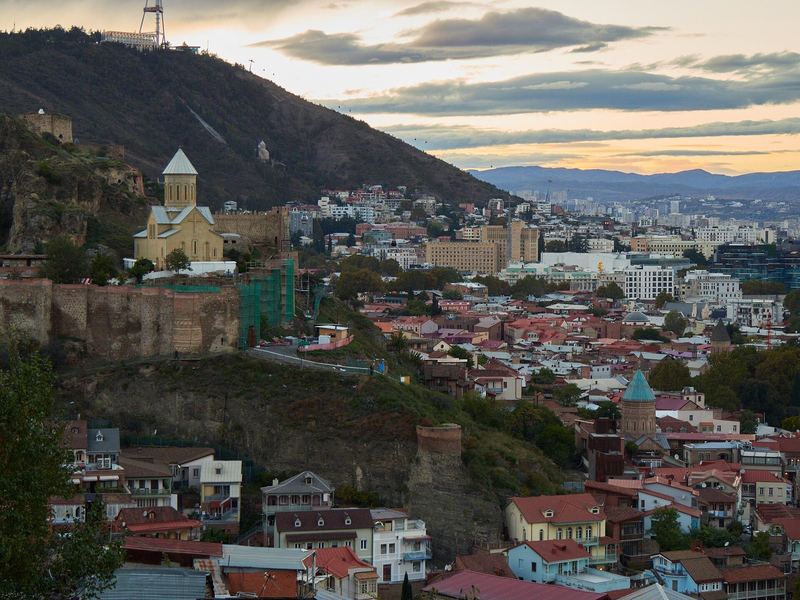
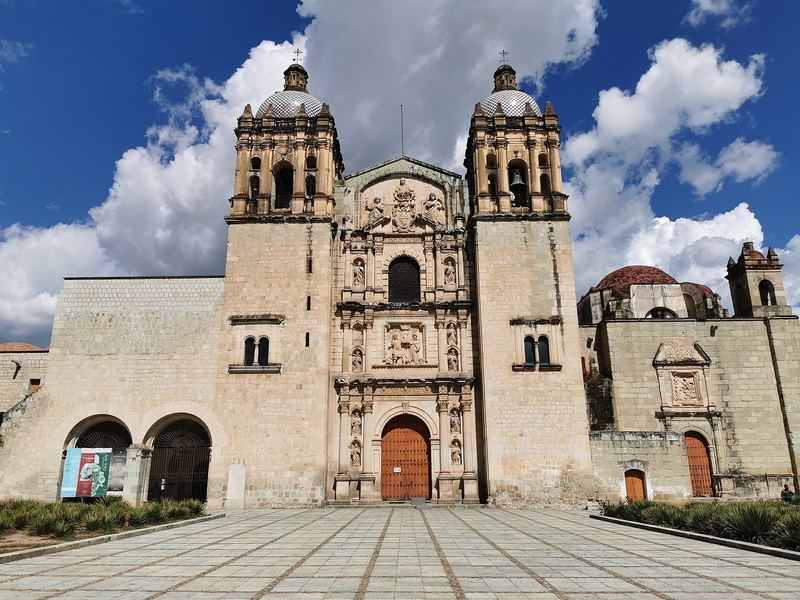
The plans that survive bad sequences are the ones that cut spending in down years, and travel makes that unusually easy: a year in Chiang Mai, Tbilisi or Oaxaca instead of Lisbon or Tokyo can halve the withdrawal without touching the quality of life. Guardrail rules (cut spending 10 percent when the withdrawal rate drifts above a threshold, raise it when below) are easy to apply when your rent is a monthly decision.
What to do with the output
Take it to a qualified adviser in your tax jurisdiction with your actual holdings, tax position and healthcare situation. Nothing here is personal financial advice, and no model labels a plan safe.
Was $40,000 pro Jahr reicht, je nach Reiseziel
| Ziel | Monatliche Kosten (komfortabel) | Abgedeckte Monate pro Jahr |
|---|---|---|
| Pai | $2,356 | 17.0 |
| Kathmandu | $2,417 | 16.5 |
| Luang Prabang | $2,771 | 14.4 |
| Siem Reap | $2,782 | 14.4 |
| Da Nang | $2,821 | 14.2 |
| Chiang Mai | $2,882 | 13.9 |
| Hoi An | $2,882 | 13.9 |
| Hanoi | $2,932 | 13.6 |
| Tirana | $2,952 | 13.6 |
| Tbilisi | $3,052 | 13.1 |
| Kuala Lumpur | $3,062 | 13.1 |
| Ho Chi Minh City | $3,184 | 12.6 |
| Antigua Guatemala | $3,214 | 12.4 |
| Oaxaca | $3,325 | 12.0 |
Live aus der Zieldatenbank: Mietschätzung für eine Ein-Zimmer-Wohnung plus tägliche Schätzung ohne Unterkunft × 30,4 im komfortablen Segment, datiert nach Reiseziel. Flüge und Versicherung nicht enthalten. Rechne deine eigenen Zahlen im Rechner für finanzielle Freiheit auf Reisen.
Quellen
- Kitces, M., Understanding Sequence Of Return Risk ↗
- Pfau, W. (2011), Safe Withdrawal Rates: A Guide for Early Retirees
Nur zur Information und Recherche, keine Finanz-, Rechts-, Einwanderungs- oder Medizinberatung. Angaben sind datiert. Vor dem Handeln anhand primärer Quellen prüfen. Teile dieser Website werden mit KI-gestützter Recherche zusammengestellt. Redaktionelle Richtlinien · Einen Fehler melden