FIRE stands for Financial Independence, Retire Early: accumulating investments large enough that their returns cover your living costs, so that paid work becomes optional. FIRE travel is what happens when someone who has reached, or is approaching, that point uses the freedom to live in motion. This site treats it analytically, with dated numbers and stated assumptions, and never as advice.
The core arithmetic
The classic rule of thumb is a withdrawal rate: spend a fixed percentage of the starting portfolio each year, adjusted for inflation, and hope the portfolio outlasts you. The 4 percent figure comes from historical US studies over 30-year horizons; longer horizons, higher fees, worse sequences of returns or lower expected returns push the sustainable rate down, and many early retirees plan at 3 to 3.5 percent. A $1,000,000 portfolio at 3.5 percent funds $35,000 a year; at 4 percent, $40,000.
Where travel changes the equation
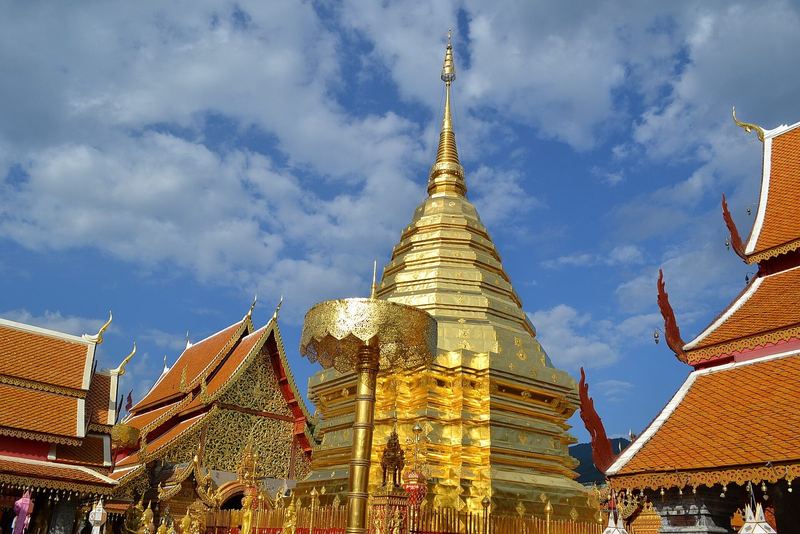
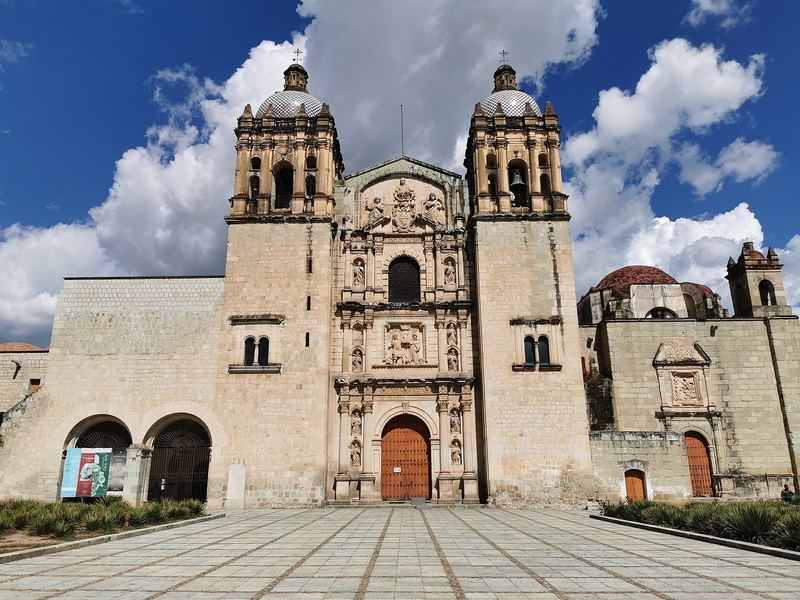
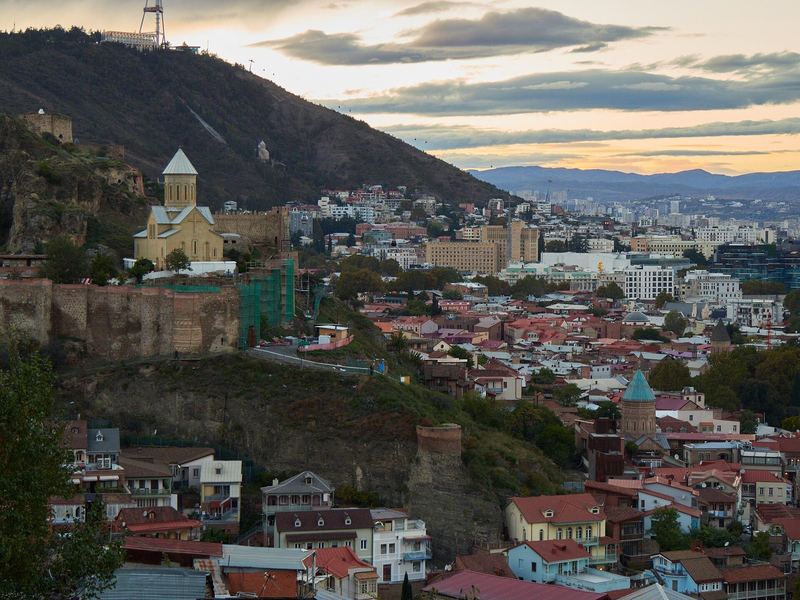
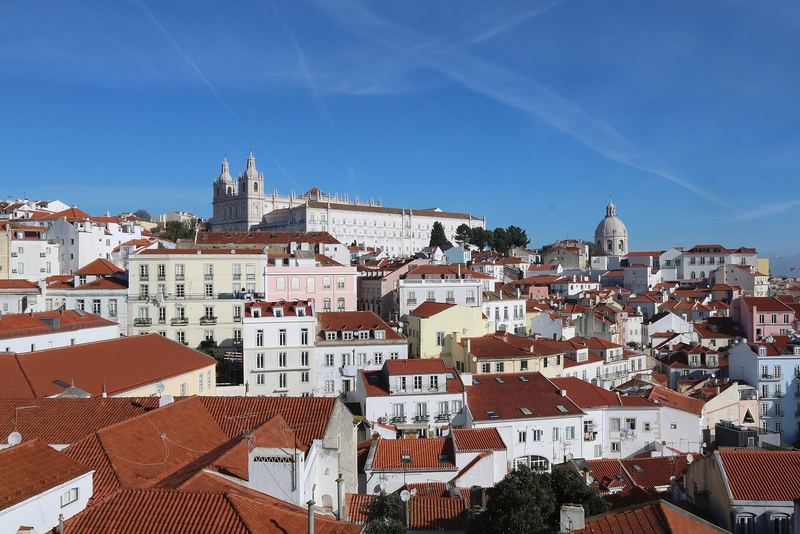
Travel does two things to that number. It can lower the cost side dramatically (geographic arbitrage: $35,000 a year is a comfortable life in Chiang Mai, Oaxaca or Tbilisi by our estimates and a thin one in Lisbon or Tokyo), and it can add costs a sedentary retiree does not have (flights, insurance, visas, the premium of never having a lease). The Financial Freedom Travel Calculator models both: a year-by-year projection with your return, inflation, fee and tax assumptions, three scenarios, an optional Monte Carlo, and a table of how many months a year your budget covers in each destination at your chosen tier.
What the calculator does not know
Your tax residency and its consequences, healthcare entitlements you may lose by leaving, currency exposure between your assets and your spending, sequence-of-returns risk in the deterministic view, the cost of returning home for emergencies, and whether you will actually enjoy it. It is an educational model; the output is a range under assumptions, not a verdict.
Healthcare
The largest unknown in most FIRE travel plans. Private healthcare in Thailand, Malaysia, Mexico, Colombia and Portugal is excellent and inexpensive by US standards; international health insurance for a 50-year-old runs roughly $2,000 to $6,000 a year depending on cover and whether the US is included; some countries' residence visas require it. Budget a healthcare line and a deductible reserve; the calculator has both fields.
Tax residency basics
Leaving a country does not always end its claim on your income; arriving in one may start a new claim after 183 days; some countries tax worldwide income, some territorial, some by citizenship. Several destinations in our database (Portugal, Spain, Greece, Hungary, Croatia, Georgia, Malaysia, Thailand) have specific regimes for foreign residents that change often. Take qualified advice in both countries; the cost is trivial against the stakes.
Currency risk
A dollar portfolio funding a euro life, or vice versa, moves by 10 to 20 percent across a few years. Our exchange-rate data (daily, indicative) shows the swings; the usual mitigations are spending in multiple currencies, holding a year of spending in the currency of the place you live, and avoiding leverage.
Travel forever, or keep a home?
The question most FIRE travellers face after two years. Keeping a base costs money and provides healthcare continuity, a tax anchor, a place for things, and somewhere to recover. Travelling continuously is cheaper and lighter and harder to sustain into the 70s. See FIRE travel vs expat retirement.
什么 $40,000 每年可支撑的目的地费用
| 目的地 | 月度费用(舒适标准) | 每年已覆盖月数 |
|---|---|---|
| Pai | $2,356 | 17.0 |
| Kathmandu | $2,417 | 16.5 |
| Luang Prabang | $2,771 | 14.4 |
| Siem Reap | $2,782 | 14.4 |
| Da Nang | $2,821 | 14.2 |
| Chiang Mai | $2,882 | 13.9 |
| Hoi An | $2,882 | 13.9 |
| Hanoi | $2,932 | 13.6 |
| Tirana | $2,952 | 13.6 |
| Tbilisi | $3,052 | 13.1 |
| Kuala Lumpur | $3,062 | 13.1 |
| Ho Chi Minh City | $3,184 | 12.6 |
| Antigua Guatemala | $3,214 | 12.4 |
| Oaxaca | $3,325 | 12.0 |
来自目的地数据库的实时数据:以舒适档位计算,一居室租金估算加上非住宿日均费用乘以30.4,数据日期以各目的地为准,不含机票和保险费用。请在 财务自由旅行计算器.
来源
- Bengen, W. (1994), Determining Withdrawal Rates Using Historical Data, Journal of Financial Planning
- Trinity Study (Cooley, Hubbard, Walz, 1998), Retirement Savings: Choosing a Withdrawal Rate That Is Sustainable
- Digital Backpacker destination cost estimates, October 2026 ↗
本站仅供研究与参考,不构成财务、法律、移民或医疗建议。相关数据具有时效性,请在采取行动前向原始来源核实。本站部分内容借助 AI 辅助研究整理而成。 编辑方针 · 报告错误